The spring cover check-in
health-and-home
The months before spring, subtly reshapes a client’s risk profile. It’s a season of settling in, fixing and refreshing our homes, and preparing for the year ahead filled with family gatherings and home entertainment.
A geyser gets replaced, a garden gets landscaped, a home office gets kitted out, or a new car arrives in the driveway. None of it feels like "insurance news" in the moment, but by spring, it can add up to a policy that no longer matches the life it's meant to cover.
That is what makes September the ideal window for a mid-year policy review.
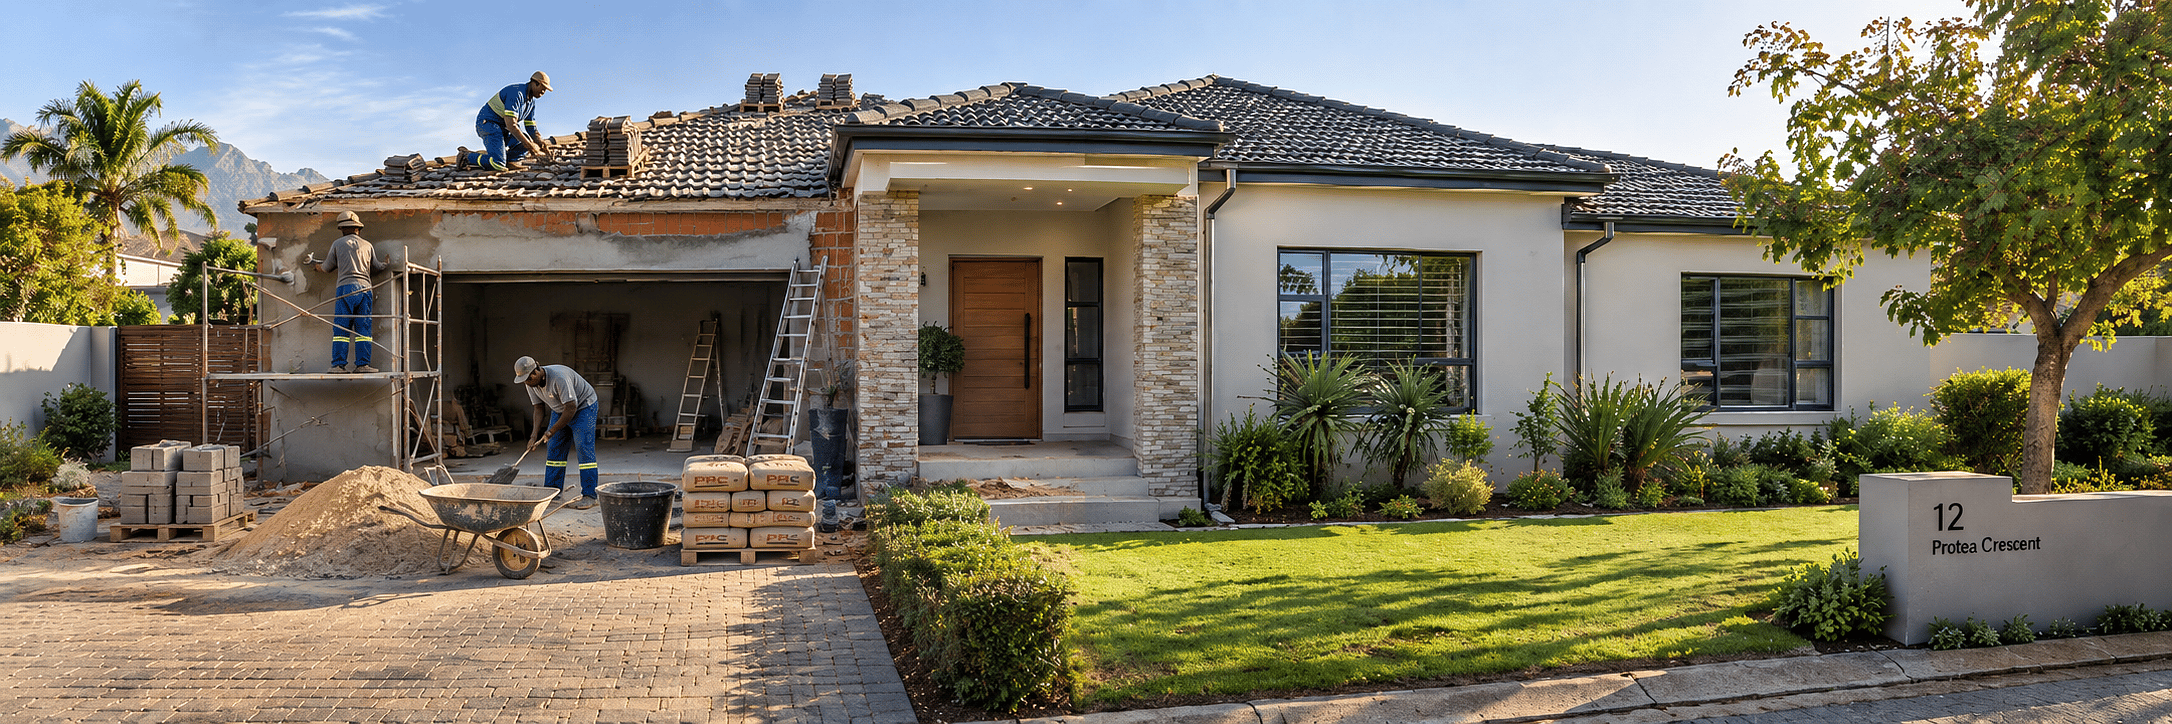
Renovations and additions often shift a property's rebuild value, meaning the building's sum insured set at inception may now be out of date. New purchases such as vehicles, electronics and appliances need to be added to your policy as soon as they are acquired to ensure they are adequately covered. Changed circumstances, from a teenager now driving the second car to a spare room turned home business, can all affect risk without ever triggering a policy change on their own.
For brokers, a spring check-in is a low-effort, high-value conversation that gives them the edge. It's not a hard sell. It's a genuine service touchpoint that protects the client’s financial wellbeing and strengthens the relationship. A few starting questions do most of the work: Has anything been built, renovated, or added since the policy started? Has a vehicle, driver, or occupant changed? Is the home being used differently than when it was first insured?
Clients don’t often think to mention these changes, which can lead to unwelcome surprises when suddenly happens. Brokers who ask achieve two things: they close real cover gaps before they become disputes, and they remind clients why having a broker matters - a real human with their wellbeing at heart.